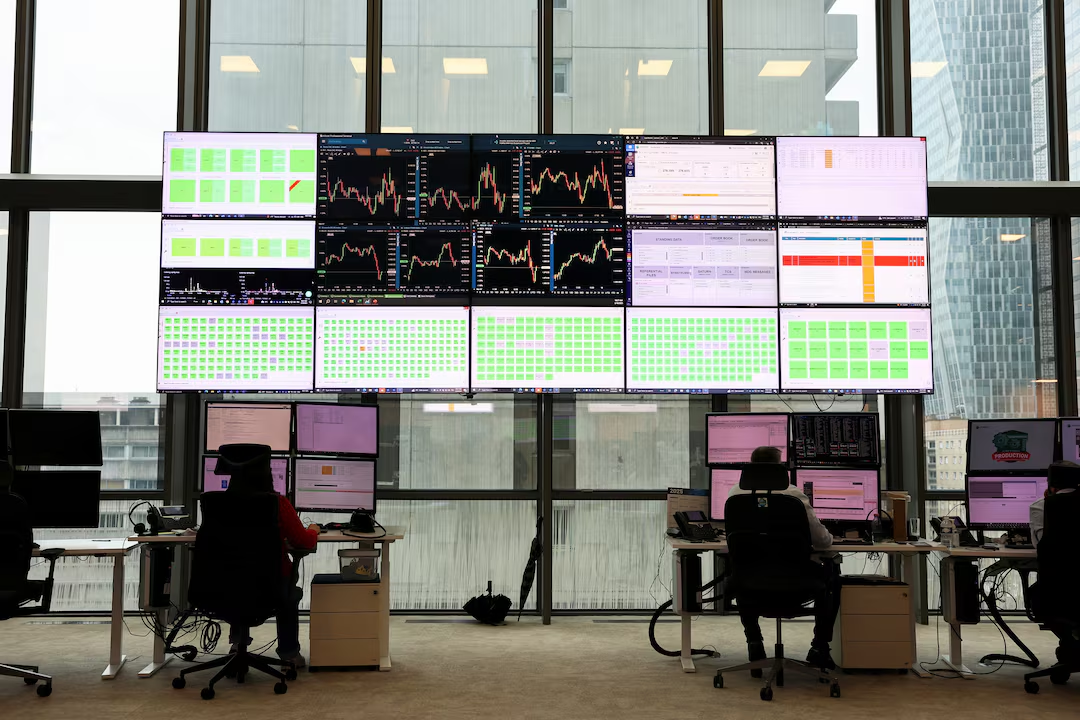
Hedge funds are facing increased scrutiny from European financial regulators after sharp movements in government bond markets raised concerns that leveraged trading strategies could amplify volatility and increase borrowing costs across the wider economy.
France has been at the centre of the turmoil, with yields on 10-year government bonds climbing towards 4.9%, their highest level in more than two decades. Investors have become increasingly concerned about the country's debt burden, inflation and political uncertainty ahead of the 2027 presidential election, while doubts over its ability to reduce the budget deficit have increased the premium demanded for holding French debt.
The European Central Bank estimates that hedge funds now account for more than half of trading in Europe's roughly $13 trillion government bond market, compared with approximately 30% in 2020. Their growing influence reflects changes in the market as central banks reduce their bond holdings and traditional investors become more selective, leaving alternative investment firms to provide an increasing share of trading activity.
The speed of the French sell-off has intensified questions about the risks associated with leveraged positions. The yield premium on French government debt over equivalent German bonds widened by nearly 25 basis points over two days, while shorter-dated securities also experienced substantial movements. Although fiscal concerns provided an underlying reason for the repricing, rapid adjustments to hedge fund positions may have contributed to the scale of the volatility.
Many hedge funds use borrowing to increase exposure to small differences between bond prices and related financial instruments. Cash-futures basis trades, for example, seek to profit from pricing discrepancies between government bonds and futures contracts, while other strategies exploit differences in interest rates or financing costs. These activities can improve market liquidity during stable conditions but become vulnerable when prices change unexpectedly.
If lenders demand additional collateral or funds reduce their exposure, investors may need to sell securities quickly to meet financing obligations. Such transactions can push bond prices lower and yields higher, potentially forcing other market participants to unwind similar positions. The International Monetary Fund has warned that hedge fund exposure to sovereign bonds has more than doubled since 2022, increasing concerns about crowded trades and dependence on short-term financing.
The potential risks are particularly important in repurchase agreement markets, where government bonds are pledged as collateral for borrowing. Banque de France data indicates that French government securities account for approximately €100 billion of the €250 billion in eurozone sovereign debt used in these transactions. In Britain, the Bank of England estimates that hedge funds account for around £85 billion of the £200 billion in net borrowing through gilt repo markets.
However, hedge funds also perform an important function by providing liquidity when governments face substantial financing requirements. The Alternative Investment Management Association has cautioned against attributing market instability to particular investors without sufficient evidence, arguing that hedge funds help maintain efficient trading conditions.
For governments, sustained bond-market volatility can increase the cost of issuing new debt, adding pressure to public finances. Higher sovereign yields also influence corporate borrowing rates, mortgage pricing and investment valuations, meaning disruption in government bond markets can affect businesses and households with little direct exposure to sovereign securities.
European regulators are consequently paying closer attention to leverage, collateral requirements and the potential for rapid selling across interconnected markets. The challenge is to identify vulnerabilities without undermining the liquidity that hedge funds provide.
The French sell-off does not demonstrate that hedge funds caused the market turmoil. It does, however, highlight how growing reliance on leveraged investors could make sovereign debt markets more sensitive to sudden changes in confidence, with consequences extending well beyond government borrowing.